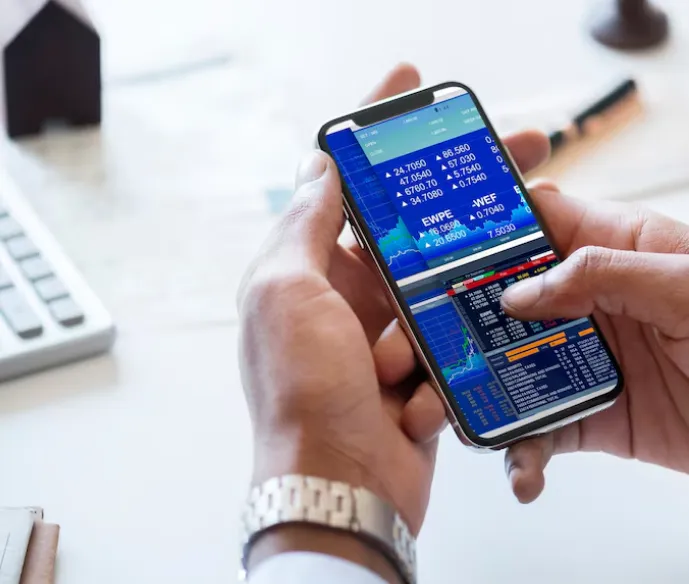
Keeping track of fund holdings means knowing what you own, what you paid, and where to find the records. A phone can bring these details into one place. It can also help you check payments and track requests without sorting through a stack of papers.
An MF Investment App can help you buy units, track holdings, and manage plans, based on the tools it offers. A Mutual Fund pools money from investors and invests it with a set goal. The app gives access to tools; the fund house manages the scheme.
Know What the App Does
An app may show your fund names, unit counts, sums paid, and values. Some apps also show due dates and let you download statements. Check which fund houses and folios it supports. A folio is your account record with a fund house.
Do not assume the screen includes every fund you own. Some holdings may need to be linked or imported. Check the list against statements from the fund house.
This helps you spot missing records before you use the total shown to review your savings.
Start with Account Checks
-
Check who runs the platform and what role it plays. It may be a fund house, distributor, or another service provider. Check the relevant registration through official sources. Read its fee terms and privacy policy before you submit your details.
-
Complete Know Your Customer checks, known as KYC. These are required for fund investments. Follow the accepted document list and check your KYC status. Do not assume that signing up for an app means all checks are done.
-
Check your bank details, mobile number, and email address. Use details you can access and keep them up to date. Read the account terms before you agree.
Read the Scheme Details
Open the scheme documents before you place a request. Check the fund’s goal, the assets it holds, and its Riskometer. This scale shows the scheme’s risk level. It helps explain risk. It cannot tell you what you will earn.
Check whether the plan is direct or regular. These plans hold the same pool of assets, but their costs differ. A regular plan includes distribution costs. A direct plan does not include distributor commission. Read the plan name in full before you buy units.
Review the expense ratio, which shows the fund’s running costs as a share of its net assets. These costs are reflected in the net asset value, or NAV. Also check exit loads and any lock in. An app’s fee is a separate item to review.
Choose How to Add Money
You may invest a lump sum or use a Systematic Investment Plan, called an SIP. An SIP lets you invest a set amount at set times. You could pay each month. Check the scheme’s rules and the sum you need to start.
Check the amount, date, bank mandate, scheme, and plan before you submit. A mandate allows bank debits on set dates. Keep funds ready for each due date. Check whether a payment went through and if you got the units. A debit alone is not the full record.
An SIP is a payment method, not a promise of profit. The value of the units can rise or fall. You can stop new payments. This does not by itself sell the units you hold. Read the platform’s process and notice periods for changes.
Understand Values and Requests
NAV is the net value per unit of a scheme. The NAV shown when you open the app may not apply to a new purchase. Which NAV applies depends on when a valid request and funds reach the fund. The scheme’s cut off rules also apply.
For a value check, suppose you hold ten units at a NAV of ₹100. Their value is ₹1,000. If NAV falls to ₹95, the value becomes ₹950. This example shows how values change. It does not include any exit load or tax.
To take money out of a scheme that allows it, you send a redemption request. Check the units or amount, bank details, exit load, tax impact, and lock in terms. Payout is not always instant. Track the request until the funds reach your bank account.
Keep Records and Access Secure
Keep passwords and one time codes to yourself. Use official support channels if a request looks wrong. Save statements and match them with app records. Check dates, units, and sums. Report gaps rather than assuming the display is complete or up to date.
Conclusion
An app can bring fund records and tasks together. Check the provider, finish KYC, read scheme terms, and review costs. Track payments, units, and withdrawals through each step. Clear records help you manage holdings while keeping market risk in view.